Fixed Income, Bonds & Deposits
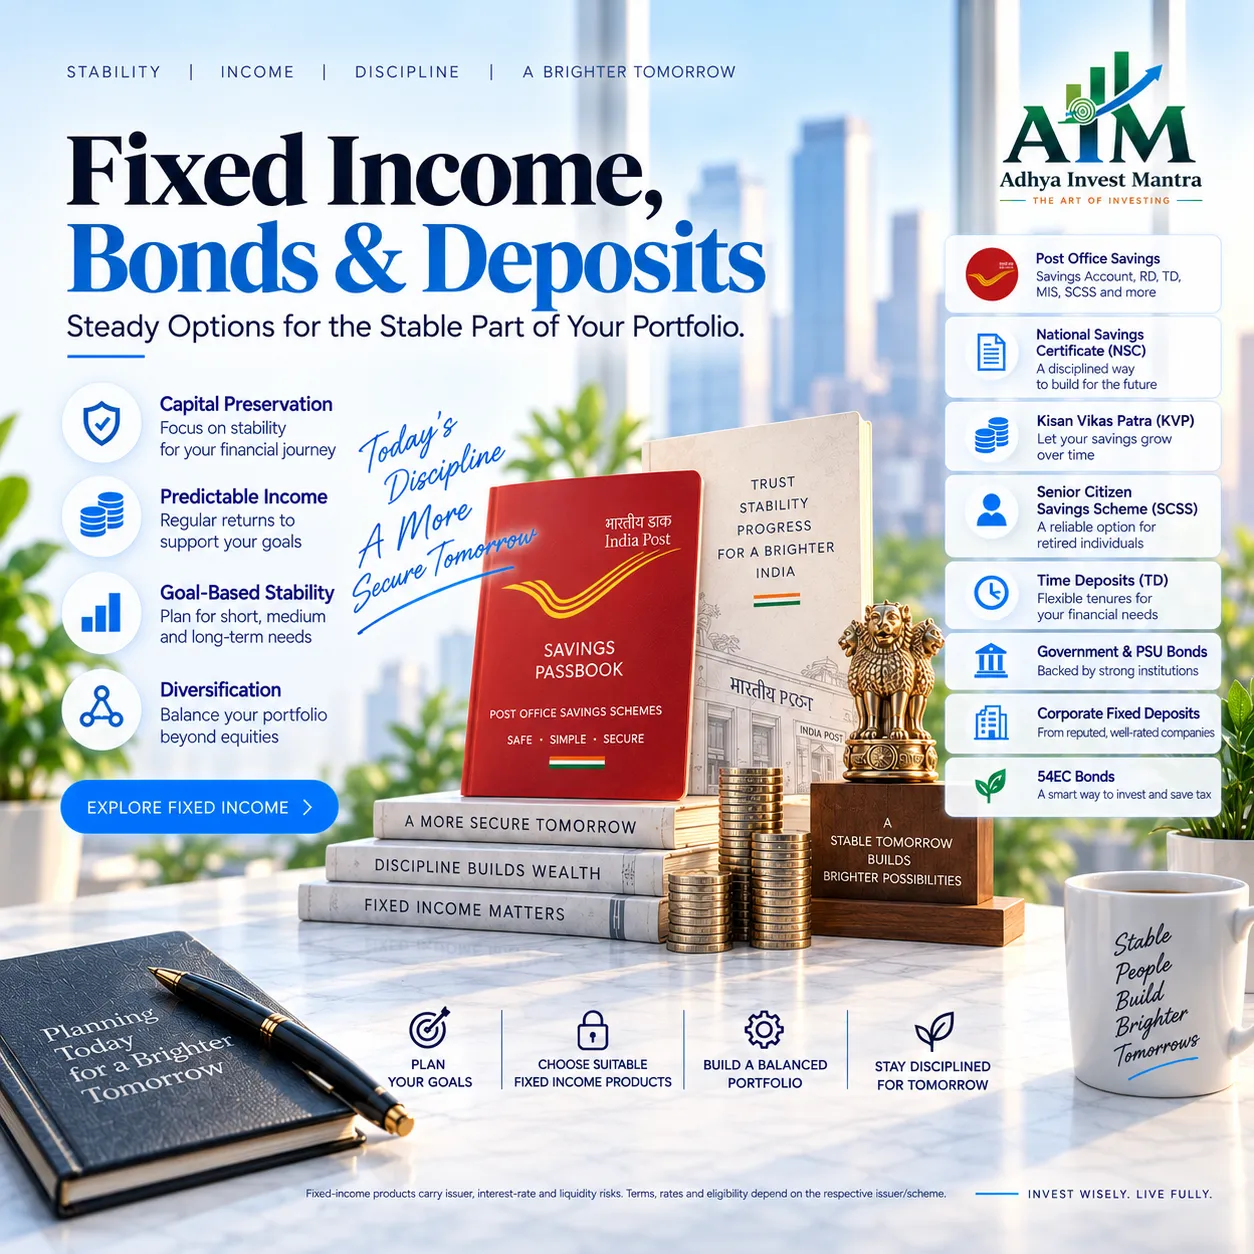
Corporate fixed deposits, government and PSU bonds, 54EC capital-gain bonds, and postal savings schemes for the stable slice of a portfolio.
Who this suits
Conservative investors, retirees who need predictable payouts, and anyone with a capital gain who needs a 54EC bond to defer tax on it.
What's included
- Corporate FDs from rated NBFCs and housing finance companies, compared on rating, tenure and payout frequency
- 54EC capital-gain bonds (REC, PFC, IRFC) for exemption under Section 54EC on long-term capital gains
- Government and PSU bonds, and Sovereign Gold Bonds when a fresh tranche opens
- Post office savings schemes — NSC, KVP, Senior Citizen Savings Scheme — for government-backed stability
How it works
Check tenure & liquidity need
How long can this money stay locked, and do you need periodic payouts or a lump sum at the end?
Compare issuers
Credit rating, tenure and payout frequency compared across NBFCs, housing finance companies and bonds.
Complete the application
Application made directly with the issuer or NBFC — funds move from your account to theirs, never through us.
Track maturity
Reminders ahead of maturity or renewal dates, so funds don't sit idle after payout.
Frequently asked
Q.Can I withdraw a corporate FD early?
Most allow premature withdrawal after a minimum lock-in (often 3–6 months), usually with a reduced interest rate. 54EC bonds cannot be withdrawn early — the 5-year lock-in is mandatory for the tax exemption to hold.
Q.Is interest taxed?
Yes, interest from corporate FDs and most bonds is added to your income and taxed at your slab rate; TDS may be deducted if interest crosses the prescribed threshold.
Q.Are these as safe as a bank FD?
No. Corporate FDs and bonds carry issuer credit risk that bank FDs (up to DICGC-insured limits) don't carry in the same way. Rating is the key indicator, and even that can be revised.
Q.What happens if the issuer's rating is downgraded after I invest?
The instrument doesn't automatically become worthless, but its risk has increased. We monitor rating actions on instruments we've recommended and will flag material downgrades.